

Low win rate
Only 18.9% of trades were profitable.
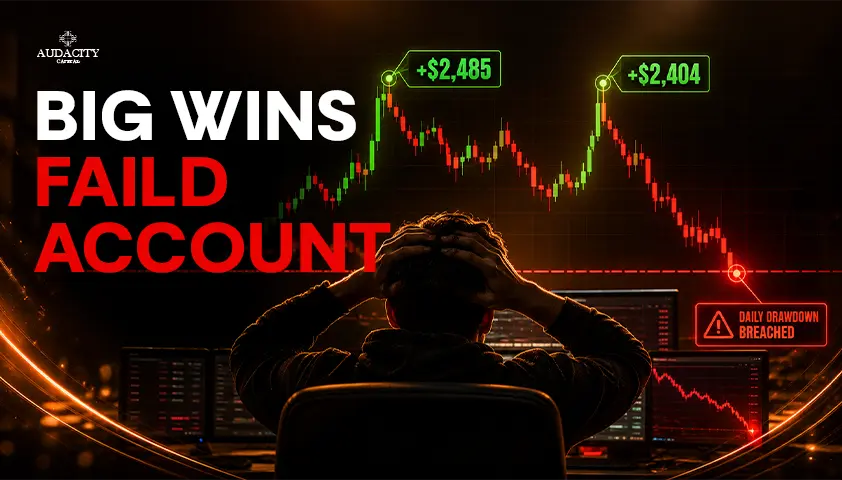
Olzhas Saukenov had a strong 3.4:1 average reward-to-risk ratio, but his 18.9% win rate was below the ~22.8% break-even level. Frequent trading, a 12-trade losing streak, limited de-risking, and continued XAU/USD positions during a losing period eventually pushed the account below its daily drawdown limit. Key lesson: A strong reward-to-risk ratio cannot overcome a strategy with an insufficient win rate and poor risk adaptation during losing streaks.
Trader | Olzhas Saukenov |
Account Size | $50,000 |
Programme | FTP |
Total Trades | 106 |
Win Rate | 18.9% |
Average Win | +$920 |
Average Loss | -$271 |
Break-Even Win Rate | Approximately 22.8% |
Estimated Expectancy | Approximately -$46 per trade |
Maximum Losing Streak | 12 trades |
Equity at Breach | $45,293.09 |
Daily Drawdown Threshold | $45,487.42 |
Breach Margin | Approximately $194.33 |
Outcome | Daily drawdown breached |
Olzhas Saukenov produced several strong winners, including profits of $2,485 and $2,404. His average winning trade was also more than three times larger than his average loss.
However, only 18.9% of his 106 trades were profitable. Frequent entries, a 12-trade losing streak and no meaningful de-risking eventually breached the account’s daily drawdown limit.
Olzhas showed that he could identify and hold profitable moves. His two strongest trades generated $2,485 and $2,404.
Position sizes also remained mostly between 0.2 and 0.4 lots. There was no clear martingale-style escalation after losses.
The average win of $920 was approximately 3.4 times larger than the average loss of $271.
However, this profile required a win rate of roughly 22.8% to break even. Olzhas achieved only 18.9%, producing an estimated loss of approximately $46 per trade.
A 12-trade losing streak exposed the weakness in the strategy.
Olzhas traded as many as nine times per day but did not meaningfully reduce his position size or trading frequency as the drawdown increased.
On September 21, Olzhas recorded his largest loss of $1,492.20 after already losing earlier that morning.
Both positions were 0.3-lot XAU/USD buys held for more than 12 hours while Gold continued falling. Instead of abandoning the losing thesis, he remained committed to the same direction.
Olzhas started with several strong winning trades and a favourable average reward-to-risk ratio.
He continued trading frequently despite the growing losing streak and drawdown.
He did not reduce his trading frequency or risk and continued holding losing Gold positions.
His 18.9% win rate produced negative expectancy, and the account eventually breached the daily drawdown limit.
Only 18.9% of trades were profitable.
Up to nine trades were placed in one day.
Size and frequency remained similar during the losing streak.
Two Gold buys were maintained against a falling market.
Five trades had no Stop Loss and nine had no Take Profit.
The account peaked at approximately +$1,837 before declining over three consecutive weeks.
Olzhas needed to reduce his trading frequency and review his entry criteria once the losing streak began.
After several consecutive losses, he should have stopped trading, reassessed the Gold setup and confirmed whether the strategy still had a positive edge before continuing.
When losses continue, step back, reassess the setup, and reduce trading frequency before taking another position.
Olzhas did not fail because of one rogue position or extreme lot sizing. He failed because a low-win-rate strategy was traded too frequently without adapting to a sustained drawdown.
A large average winner means little if the strategy does not win often enough to survive its losing streaks.
Ask yourself:
When the data shows that the current approach is failing, continuing to fire the same setup is not discipline. It is refusal to adapt.
Success Follow-up
Every trading setback can provide valuable lessons for improving discipline, risk management, and decision-making. By understanding what went wrong and adapting the process, traders can turn difficult experiences into opportunities to build a more consistent approach.
Asim begann mit einer geduldigen und kontrollierten Vorgehensweise, doch sechs aufeinanderfolgende Verluste bei Gold am 18 führten zu erhöhtem Risiko, impulsiven Entscheidungen und einer Überschreitung des täglichen Drawdowns. Die wichtigste Erkenntnis daraus ist, dass es wichtiger ist, nach wiederholten Verlusten aufzuhören und das Kapital zu schützen, als zu versuchen, Verluste sofort wieder auszugleichen.
Philip Ezekiel durchbrach den täglichen Drawdown, nachdem er seine anfänglichen Risikokontrollen aufgegeben hatte, was zu einer verlorenen Goldposition beitrug, indem er ohne Stop-Losses handelte, Verluste manuell schloss und während eines eingeschränkten Nachrichtenfensters handelte.
Chinonso Ogbonna’s account suffered after an oversized first trade caused a 3.1% loss, followed by repeated entries, revenge trading and a ten-trade losing streak. Although he used Stop Losses and avoided prohibited practices, poor risk sizing and failure to pause after losses allowed the drawdown to escalate.