

Iceberg Orders Explained: How Hidden Large Orders Work


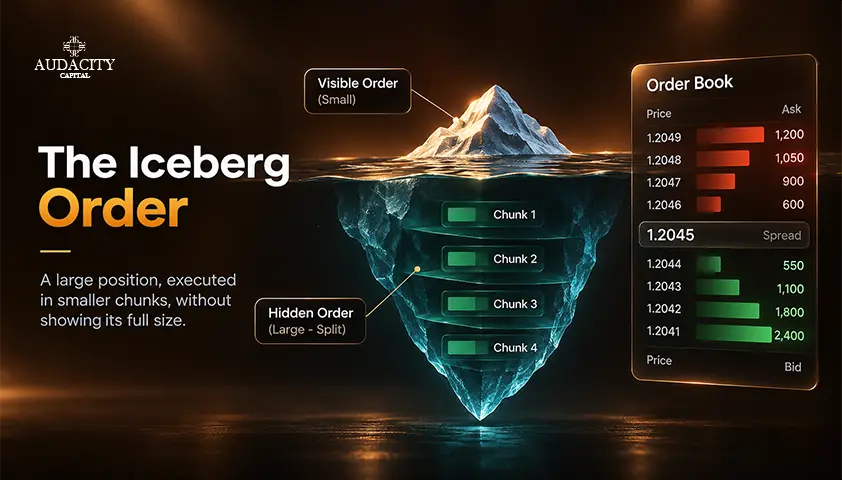
Suppose a trader wants to trade a really huge amount of shares. If such a big order sits in the trading order book, everybody will be able to see that. Some will readjust the prices, retract their bids, or even take up positions ahead of this order. And the size of the order itself begins to act against the trader.
Iceberg orders help avoid all this by showing only a fraction of the quantity of the order while the other part remains hidden from the public market depth.
In this article we will discuss the mechanics along with examples, why traders use them, differences between platforms, possible hidden liquidity, and limitations.
What Is an Iceberg Order?
As the name implies, an iceberg order is designed to trade a big order while revealing only a small portion of it to other traders on the exchange at any time.
There are three main characteristics that are used to describe an iceberg order:
- Total order size: the whole size of the order that the trader wants to buy or sell.
- Displayed order size: the part that is now visible in the order book.
- Hidden or reserve order size: the part that is not visible.
In case the displayed part executes, the new part can be displayed, or a new child order can be submitted. Which of those situations occurs depends on the trading venue or platform, thus, the meaning of the term can differ.
Iceberg orders are typically used when a large order needs to be placed, but the size of the order will reveal the intentions of the trader or will impact the price the trader receives.
How Do Iceberg Orders Work?
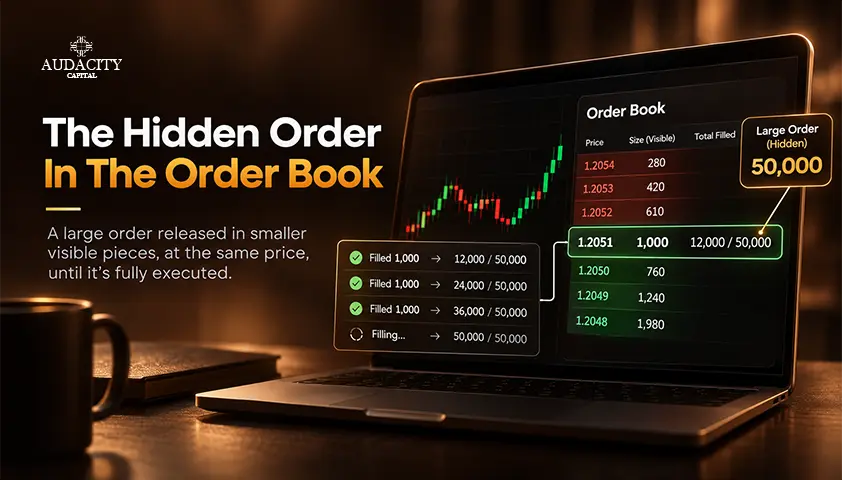
Let’s start with the conceptual description. A trader selects the total quantity of the order, its price or execution instruction, and the visible part of the quantity. The latter is the amount that will be shown in the order book.
Then, as the visible quantity gets filled, a new quantity becomes available either by replenishing the visible part from the hidden pool of orders or by submitting it as a new child order.
The Kraken exchange uses the first method: a trader specifies the total quantity and display quantity; the rest remains hidden and gets replenished as the display quantity is filled.
Zerodha employs the second method: a large order is split into sequential parts and the next one becomes visible only after execution of the previous part.
From the outside, both systems look like an iceberg order in the trading world. From inside, however, they differ in the way they work, and this difference influences:
- order priority
- how and when execution happens
- fees
- platform restrictions
Those points are addressed in more detail in the platform section below.
Iceberg Order Example
Here is a basic and hypothetical example. A trader wants to buy 10,000 shares at ₹500, but doesn’t wish for the entire interest of 10,000-shares to be visible.
They decide to go for the iceberg type of order which has a total quantity of 10,000 shares and visible quantity of 1,000 shares.
Firstly, only 1,000 shares are seen at ₹500 in the order book. Once 1,000 shares are filled, another 1,000 shares will become visible or submitted based on the platform’s behavior.
The process repeats until the whole 10,000 shares are filled, the remaining quantity gets canceled, or the market conditions prevent further fills.
Stage | Visible Quantity | Remaining Quantity |
Initial order | 1,000 | 9,000 |
After first portion fills | 1,000 | 8,000 |
After second portion fills | 1,000 | 7,000 |
Continue until completed | Varies | Varies |
This is a simplified illustration. Real platform behaviour can differ in how slices are replenished, how quickly, and under what rules. This structure does not guarantees that all 10,000 shares will fill at ₹500.
It is important to keep order size hidden since, in the case of large orders, the order becomes the market information itself. There are four reasons.
Why Do Traders Use Iceberg Orders?
It is important to keep order size hidden since, in the case of large orders, the order becomes the market information itself. There are four reasons.
Reduce Information Leakage
An extremely large visible order could indicate a buyer or seller in the market. Other traders would react before the order is completely executed.
Minimize Market Impact
Execution or signaling of a large amount can use up liquidity at multiple price points. Iceberg execution divides that process in small amounts.
Manage Impact Cost
The impact cost refers to the worsening of execution as a result of the order size of the trader passing through the available liquidity.
Execute Large Orders More Discreetly
Institutions and other large traders may want to establish or exit a position without broadcasting their full intended size.
None of this hides the activity. In fact, continual resupply can itself hint that there is hidden liquidity, so iceberg orders hide risk instead of eliminating it.
Iceberg Orders Do Not Work the Same Way on Every Platform
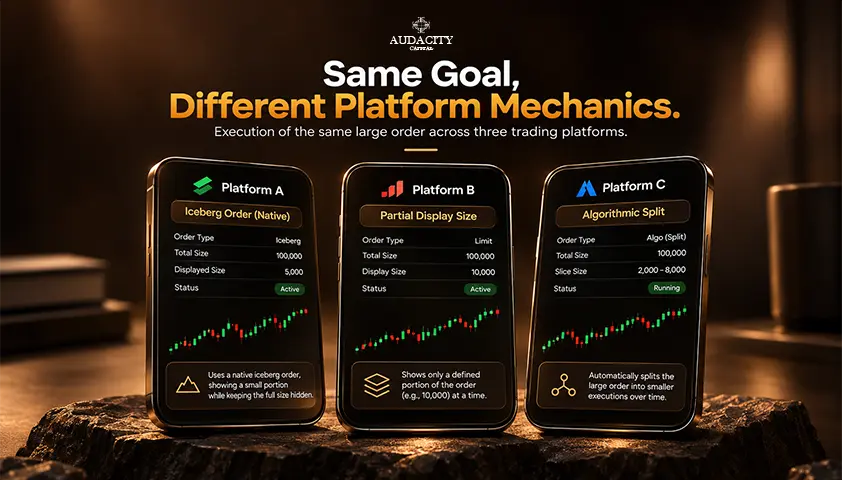
There is a misconception about iceberg orders is that all icebergs have identical instructions, but it’s not. There are two main types of them.
Exchange-Native Iceberg or Reserve Order
The exchange sees the full order while allowed only the displayed quantity to be seen by the market data. As the display size gets executed, reserve size becomes visible based on the exchange matching logic.
Broker or Platform-Generated Iceberg
The platform keeps the parent order but submits smaller child orders one by one. The exchange will see only the active child order, not the total parent size.
Currently, Zerodha says it handles its iceberg orders internally instead of seeing as a whole exchange-native hidden order. Similarly, Trading Technologies also supports the parent order where child orders are submitted in sequence, including fixed or variable child quantities.
Why the Distinction Matters
The execution can impact:
- queue priority
- pricing
- child-order timing
- order types allowed
- brokerage and fees
- cancellation behaviour
- minimum quantities
- venue restrictions
Prior to using any definition of "iceberg," find out how it is defined at your particular exchange or trading platform.
Advantages and Limitations of Iceberg Orders
Iceberg order solves the problem of order exposure. But it does not affect the real amount of liquidity. The table matches each potential advantage with its actual disadvantage.
Potential Advantage | Limitation |
Hides full intended quantity | Repeated fills can still reveal hidden interest |
May reduce market impact | Does not ensure a better price execution |
Can minimize signalling | Entire order may not fill |
Helps to handle big orders | Multiple child orders may create additional fees |
Provides more control over execution | Specifics depend on the platform or venue |
Can help work around single-order size limits on some platforms | Slicing does not remove liquidity constraints |
In case the liquidity is insufficient at the selected price level, hiding the order will not make the execution happen. It is also possible for the market to move in the meantime, thus leaving the trader partially executed at prices that were not anticipated.
How Can Traders Spot a Possible Iceberg Order?
The very question of identifying iceberg orders has one crucial limitation: the regular displayed depth does not provide the information about the total hidden size, and no particular pattern proves the presence of the iceberg. The traders can only look for the specific combinations of behavior that suggest a possible iceberg..
Repeated Replenishment at the Same Price
The displayed size trades first, then another size of similar quantity emerges at the same price level. Academics studying the topic of iceberg orders have identified repeated replenishment of liquidity as one of the methods through which the market discovers the presence of iceberg orders.
Executed Volume Exceeds Previously Visible Size
The price level executes way more size than was available in the order book. That gap can point to hidden or replenishing liquidity.
Repeated Transactions Without Price Progress
The aggressive buying or selling occurs on a particular level but no progress occurs in the price.
Absorption
Continuous execution against resting liquidity without a corresponding movement in price is referred to as absorption. BookMap links iceberg orders with this general order flow pattern.
A Critical Point: None of these patterns alone is a clear indicator of the presence of an iceberg order. They could also be the result of a variety of actions by different traders, rapid replacement of normal limit orders, algorithmic execution, or market-making activity.
What Can Iceberg Orders Tell You About Market Liquidity?
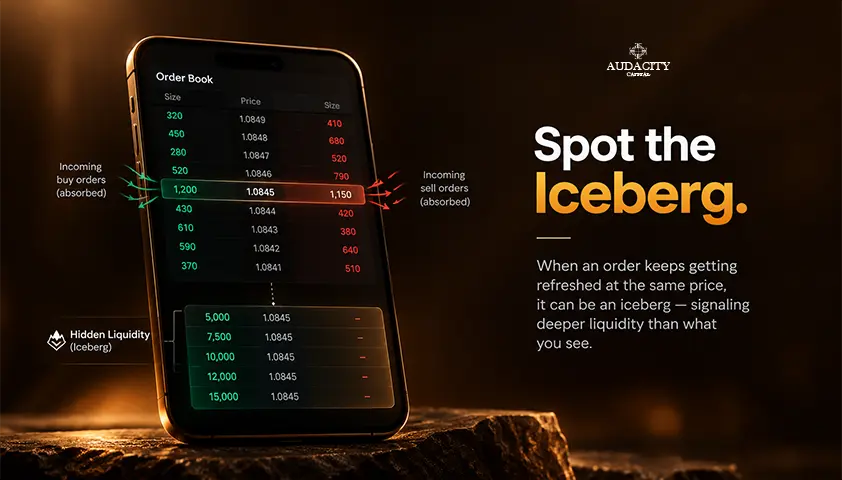
If you never place any iceberg order, you might still be able to use the presence of suspected iceberg orders to know that the liquidity displayed at that level is lower than the real available liquidity.
Take for example a situation where a trader sees large and aggressive bids going at the ask, while price does not go up. This could mean that there is a lot of hidden or replenishing selling liquidity. The same is true about selling at the bid, which may suggest hidden buying interest.
It needs to be understood that iceberg orders alone do not tell you whether the situation is bullish or bearish. Its meaning depends on:
- which side is absorbing it
- whether there is some hidden liquidity
- what will happen after the liquidity dries out
- and other factors that are relevant to the market environment.
The importance lies in context. Understanding that a level contains more size than what is displayed will allow for better order book reading skills, but it is just one piece of information that you must analyze in order to trade properly.
Iceberg Orders vs Hidden Orders vs Disclosed Quantity
The three concepts are often confused, and their use varies depending on the exchanges and platforms.
Order Type | What the Market Sees | Basic Mechanism |
Iceberg Order | Only part of the intended size | Hidden reserve or sequential disclosed slices |
Fully Hidden Order | No displayed quantity | Order rests without being publicly displayed where supported |
Disclosed Quantity Order | A predefined portion | Exchange displays only the disclosed portion of the larger order |
Do not assume that these orders have the same priority, charge, and execution characteristics. This table gives a description of the idea. The exact handling will be determined by your exchange and trading platform.
Are Iceberg Orders Legal?
Yes, iceberg orders are legal order types or execution methods when the applicable exchange, broker, or trading platform permits them. There is nothing illegal about concealing part of an order intended to be executed.
The key distinction between iceberg orders and spoofing is that the former is an expression of genuine trading intentions while the latter is an attempt to mislead through displaying fake orders.
This is only informational material. Trading regulations vary depending on markets and jurisdictions.
Iceberg Orders Reveal Why Visible Liquidity Is Only Part of the Market
The quantity displayed in an order book does not always represent the full amount of buying or selling interest at that price. Iceberg orders let large traders manage how much of their intention becomes visible, though implementation varies between exchanges and platforms.
For anyone observing the market, repeated replenishment and absorption can add useful context about hidden liquidity, but they are not standalone trading signals. Before using any order type labelled "iceberg," learn exactly how your venue or platform handles it.
Frequently Asked Questions
Large institutions are natural users because order exposure matters more as trade size grows. However, some retail trading platforms also provide iceberg or order-slicing functionality. Availability, minimum order size, and exact implementation depend on the broker, exchange, or trading venue.
It depends on market structure and platform support. Centralised crypto exchanges can offer iceberg functionality, as Kraken currently does. In forex, there is no single global central order book for the entire spot market, so whether iceberg-style functionality exists depends on the specific liquidity venue, institutional platform, or execution system. Not every forex broker supports it.
There is no universal answer. Some exchange-native disclosed or reserve mechanisms follow venue-specific priority rules, while broker-generated sequential child orders may enter the market as new orders. Check the relevant exchange or platform documentation rather than assuming every replenished slice keeps the original order's priority.
Prêt à appliquer un risque discipliné aux cryptos ? Explorez les nouveaux instruments crypto d'Audacity Capital et apportez votre stratégie de trading.
En savoir plusNewsletter
Rejoignez notre newsletter pour rester informé.
Rejoignez Notre Communauté Sociale
Commencez Votre Voyage Aujourd'hui Avec Notre Essai Gratuit
Affichez fièrement vos compétences et réalisations grâce à des certificats et obtenez la reconnaissance de votre travail acharné et de votre dévouement auprès d'investisseurs potentiels et de pairs.
Essai GratuitArticles Connexes
Stochastic Oscillator vs RSI: How They Differ and How to Use Them
Compare RSI and the Stochastic Oscillator, understand their signals, and choose the right indicator for your trading strategy.

Stochastic Oscillator
Learn how to use the stochastic oscillator in trading, interpret overbought and oversold levels, spot crossovers, and adjust settings.
Backtesting vs Forward Testing: How to Validate a Trading Strategy
Compare backtesting vs forward testing, learn how each works, why results differ, and how traders use both to validate a trading strategy.
Bid and Ask Price Explained: What Every Trader Needs to Know
Learn what bid and ask prices mean, how spreads affect trading costs, why spreads widen, and how to manage them when trading forex and other markets.