

Maximum Favorable Excursion: How MFE and MAE Read a Trade


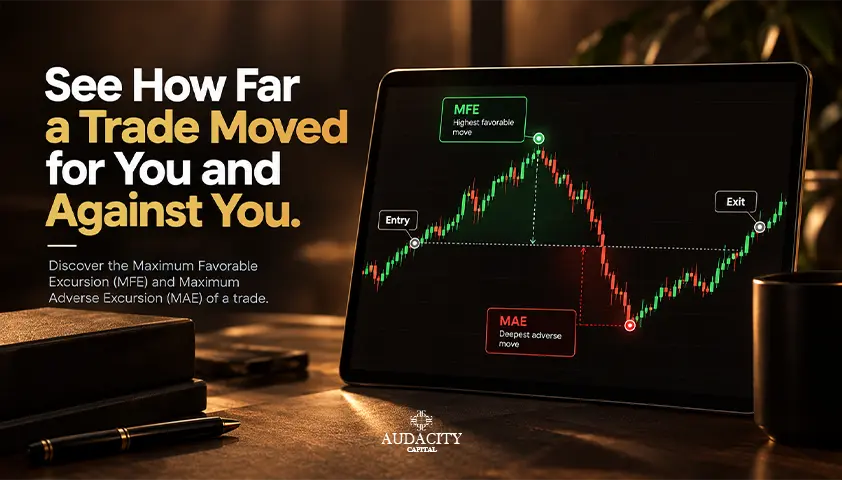
Two trades produce the same profits. One has a nice run in your favor, takes little heat and exits close to its target. The other has a huge hit, travels far and fast, then gives away most of it before you exit. Final P&L considers them equal.
But Maximum Favorable Excursion offers a different picture. MFE tracks the maximum open gain, while MAE follows the worst open loss. This article includes formulas for both, the MFE-to-exit gap, paired interpretation, rule testing and data problems.
MFE and MAE Show What Final P&L Hides
Maximum Favorable Excursion is the highest price excursion or the maximum amount of unrealized gain during the time interval between entry and exit.
Maximum Adverse Excursion is the maximum excursion (or maximum unrealized loss) for the period between entry and exit and measured in the same manner.
Measure | What it records | What it does not establish |
MFE | The most favorable point reached during the course of the trade. | The actual gain or a real-time maximum that you might know. |
MAE | Most adverse price excursion while the position was open. | The realized loss or the correct stop distance. |
Realized P&L | The outcome at the executed exit using the given cost method. | The best and worst points discussed earlier. |
Why read them together? MFE gives you the opportunity, MAE gives you the heat and the exit gives you the profit booked.
A profitable trade with high MFE and low MAE took a very different course compared with a trade of the same profit following a significant adverse move. MFE vs MAE is not a comparison of two values. It's an assessment of one trade from two perspectives.
Here comes a definition note. There may be several words used on your platform to indicate those two concepts: favorable excursion, adverse excursion, run-up, or drawdown. Make sure to check what meaning lies behind those words when comparing two reports.
Calculate MFE and MAE With One Price Convention
The maximum favorable excursion formula varies based on the direction of the trade. So it makes sense to list both the long and short versions next to each other.
Use only non-negative numbers for both metrics. Some platforms show adverse movements below zero or use a different P&L convention.
Direction | MFE formula | MAE formula |
Long | Highest eligible price while open - entry price | Entry price - lowest eligible price while open |
Short | Entry price – worst eligible price while open | Best eligible price while open – entry price |
This is how MFE is calculated depending on trade direction. Best price reached determines the favorable number, while worst price reached determines the adverse number.
Report Both Excursions in a Useful Unit
The MFE and MAE can be displayed in points, pips, percentage, account currency or R multiples. When reporting MFE and MAE in the price unit, they reflect raw market movement.
Reporting MFE and MAE in account currency makes it possible to report the open P&L and open risk in monetary terms. Using R-multiple allows comparison of trades with identical initial-risk assumptions.
Fixed Size and Changing Size Need Different Math
In case of fixed position size, MFE and MAE in terms of currency may be calculated as the price difference multiplied by quantity and point value. For scaling in or out, such an easy way will not be possible. Instead, you have to monitor the peaks and troughs of the running Open-P&L series.
You can also work out the value of each position at each time period. You should not multiply the extremes of the price times the final or largest size afterwards, since the extremes were not always available at all prices.
There is one universal rule of measurement which becomes the basis for all of the above: consistency.
When comparing two metrics, ensure that you use the same time scale, price source, bid/ask conventions, costs, bar interval, and partial exit. MFE and MAE calculation becomes meaningless in case of different measurement techniques.
A Worked Example With One Trade and Four Numbers
Assume that you have a fixed long position. Entry at 100, lowest possible price at 97, highest possible price at 108 and exit at 104. In the first pass, disregard costs, and in any real study, include costs.
Observation | Calculation | Result and meaning |
Maximum Favorable Excursion | 108 minus 100 | 8 points of favorable movement |
Maximum Adverse Excursion | 100 minus 97 | 3 points of adverse movement |
Realized price gain | 104 minus 100 | 4 points booked at the exit |
Profit giveback from peak | 108 minus 104 | 4 points surrendered before exit |
The sequence of the price moves is as important as the values. First, the price dropped from 100 to 97, marking the intratrade low. It then climbed to 108 before retracing its steps to the exit at 104.
In the absence of this sequence, the same MFE and MAE would apply to another case of management problem. One single trade cannot create a pattern.
Take note of the output. This trade managed to get 4 out of 8 positive points after having 3 negative points. This does not mean that the enty or exit was bad.
The strategy might be to deliberately accept pullbacks, or it could be for a bigger move. MFE brings up an issue of trade management. It doesn't make a judgement.
The MFE to Exit Gap Turns Missed Profit Into a Testable Question
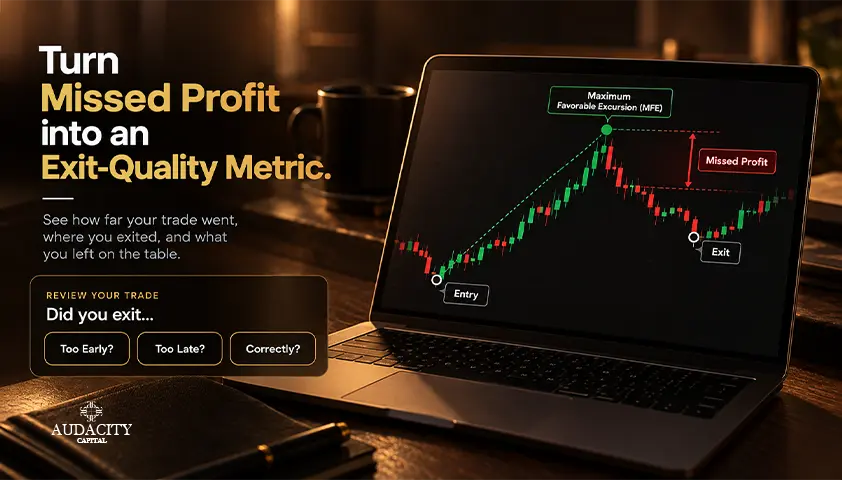
Profit giveback is defined as the gap between the maximum open profit and the realized gain with one cost convention throughout. A basic MFE capture ratio is simply realized profit divided by MFE. Apply it where the denominator is valid and where all trades are treated similarly.
Efficiency of exit is captured by this idea: how much of your move did you keep?
Pattern | Question to ask | Do not assume |
High MFE, reasonable profit | Was too much open profit left open by the exit rule? | That every trade could close at or near the top |
High MFE, final loss | When did the trade lose its favorable state? | That moving the stop to breakeven always helps |
Low MFE, small win | Was there only a small move available from the setup? | That holding longer will be a benefit |
MFE similar to realized profit | Are the exits always efficient, or just lucky? | That a high capture ratio alone proves a strong strategy |
What would be an ideal MFE capture ratio then? There is no magic percentage applicable to scalping, trend following, fixed target, scaling and partial exit trades.
Scalpers and trend followers would be located in entirely different ranges and that does not necessarily make one or the other wrong. Compare the system to its own statistics and performance.
Read MFE and MAE Together as Four Trade Path Stories
That is when trade excursion analysis comes into play. Don't judge the names by numbers and try to notice the pattern that keeps repeating.
Trade path | MFE, MAE, and exit relationship | Likely review area |
Clean move | Meaningful MFE, small MAE, and an exit that follows the planned rule | Check whether the behavior persists after costs and across regimes |
Recovery winner | Meaningful MFE and realized profit, but MAE was also large | Review entry timing, stop tolerance, and reward earned for the heat taken |
Round trip | Meaningful MFE followed by a flat or negative exit, with MAE before or after the peak | Review event order, thesis failure, and allowed profit giveback |
No expansion | Small MFE with meaningful MAE or a loss | Review setup quality, timing, volatility, and whether the expected move appeared |
Repeat patterns and sequence of events is the key. A single recovery win or a round trip may be typical for your strategy.
Pay special attention if these occur in connection with one setup, one direction of trade, or one trading session. That repetition may reveal something worth testing.
Use MFE and MAE Distributions to Test Trading Rules
Distributions of MFE and MAE should form hypotheses rather than change your rules immediately. Follow a disciplined process, not rush to modify your rules just seeing some numbers.
Step | Action | Output |
1. Freeze the sample | Use one strategy, setup, market, side, holding style, and rule version | Comparable trades |
2. Preserve the path | Keep entry, exit, ordered intratrade prices, size changes, costs, and initial risk | Auditable MFE and MAE values |
3. Plot both distributions | Review medians, percentiles, spread, and outliers in points, currency, or R | Typical favorable and adverse movement |
4. Compare with outcomes | Plot MFE and MAE against realized P&L and label the exit reason | Repeated entry, heat, giveback, and capture patterns |
5. State one hypothesis | Test a later entry, stop rule, fixed target, trailing rule, or later first partial | One rule that can be replayed |
6. Replay in order | Recalculate the whole trade path, fills, costs, win rate, payoff, expectancy, and drawdown | Strategy-level effect |
7. Validate separately | Check the frozen rule on data not used to design it, then monitor paper or small live execution | Evidence beyond the design sample |
Test Entry, Stop, and Exit Changes Separately
Do not lump together a later entry, a tighter stop, a fixed target, a trailing rule, and a partial exit into a single test. Test them separately so you can discern the results of each adjustment.
MAE reduction might come with missed winners. Tightening of the target might improve the winning percentage at the cost of larger winners. Trailing stops might lower givebacks at the expense of increased sensitivity to market noise.
There is one warning regarding the sequence that is worth highlighting. The figures for MFE and MAE tell nothing about the order of extremes, or whether the proposed stop would cut out the trade before any positive extreme would occur. A replaying of the sequence is a must.
TradeStation, for instance, can produce an MFE graph, which gives an idea what level of trailing-stop could be used. However, you still need to retest the stop candidate against the entire trade sequence.
The details of such a test are provided in our guides on backtesting, walk-forward analysis, and Monte Carlo simulation.
When MFE and MAE Numbers Are Not Comparable
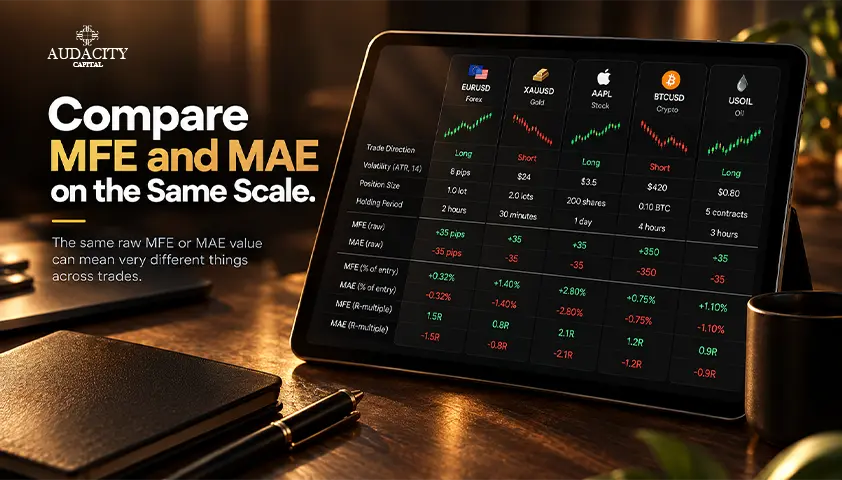
Two excursion values can look comparable and still be measuring different things. Watch for these data issues before you trust a side-by-side read.
Data issue | Why it changes the excursions | Writer guidance |
Bar data instead of tick data | A bar high or low may not preserve the path or the executable quote sequence | State the timeframe and whether intrabar data was used |
Bid, ask, and spread | The chart extreme may differ from the price available to close the position | Use the platform's documented valuation convention |
Scaling in or out | The full position was not present at every price extreme | Prefer running P&L or reconstruct size through time |
Missing live data | The recorded best or worst price may exclude gaps in the feed | Check feed continuity before treating a value as complete |
Mixed strategies | Trend, scalp, long, short, and session trades have different shapes | Segment before averaging |
Gross versus net values | Costs and slippage can change capture and final profitability | Keep gross and net analysis clearly labeled |
As a platform example, TradingView documents favorable excursions as maximum unrealized profit inside its strategy report.
NinjaTrader notes that real-time and backtest values can draw on different observations. The lesson is not that one platform wins. The lesson is that you must state your method, because bar data and tick data will not always agree.
Keep Trade Excursions Separate From Account Drawdown
Trade-level excursions answer a different question from account-level drawdown. Do not mix them.
Metric | Reference points | Question answered |
MFE | Entry to the best favorable point before exit | How far did this trade move in favor? |
MAE | Entry to the worst adverse point before exit | How far did this trade move against the entry? |
Realized P&L | Entry and executed exit, including stated costs | What result was booked? |
Profit giveback | Best open result to realized exit | How much open profit was released before closing? |
Account or strategy equity peak to a later trough | What was the deepest historical decline? |
This article explains maximum adverse excursion because the pair belongs together.
For the deeper work, including full adverse-excursion formulas, MAE scatter plots, and stop-validation examples, use our dedicated MAE guide rather than duplicating that workflow here.
What Maximum Favorable Excursion Means for Funded Traders
A large open profit is not a realized result. Likewise, a deep open loss is not erased simply because the trade recovered. Both describe how you handled capital.
Repeated high MFE giveback can point to an exit-discipline problem. Repeated high MAE can expose an entry or risk problem that your win column hides.
- Review MFE, MAE, and giveback by setup, session, market, and exit reason.
- Separate rule-following trades from emotional overrides, so you measure your plan and not your impulses.
- Do not widen risk or remove a stop just to improve capture. A better capture number earned by abandoning your stop is not progress.
- Check your current funded-program rules before you assume how floating P&L affects any daily or maximum drawdown calculation.
This is evergreen metric education, so confirm live program terms directly rather than relying on figures in a guide. Excursion analysis encourages you to review the entire trade, not just its exit. That habit can support more disciplined funded trading.
Build a Small MFE and MAE Review Sheet
Copy this compact checklist into your trading journal or a spreadsheet and fill one row per trade.
Field | What to record |
Trade identity | Date, market, direction, setup, session, and rule version |
Risk basis | Initial stop and initial risk in currency or R |
Price path | Entry, best eligible price, worst eligible price, and exit |
Execution path | Position-size changes, partial exits, and exit reason |
Results | MFE, MAE, realized P&L, giveback, and costs under one shared convention |
Review tag | Rule followed, early exit, round trip, target hit, or data issue |
Check comparable groups of trades and not individual rows only. This sheet is a research tool and a road map to discovering your trading edge. It is not an excuse to manage your next real trade using an average alone.
Conclusion
MFE tells you the optimal trade, MAE the worst case, and P&L the reality of how much you really made. If the same connection keeps showing itself on similar trades, then that is something to test out, not a formula for a perfect entry, stop, or exit.
Frequently Asked Questions
Maximum Favorable Excursion is the greatest favorable price move, or open profit, recorded between entry and exit under a stated measurement method. It describes the best point the trade reached while open, not the profit you actually realized at your exit.
MFE records the best favorable move while the trade is open. MAE records the worst adverse move over the same window. Neither is the final result. Realized P&L is the result booked at your executed exit.
For MFE on a short, subtract the lowest eligible price from the entry price. For MAE, subtract the entry price from the highest eligible price. Convert to currency separately, using running P&L if your position size changed.
Yes. A volatile trade can travel far on both sides of the entry. The order of the two extremes, plus the final exit, determines what the pattern actually means for your management.
There is no universal target. The useful level depends on strategy, holding period, scaling, costs, and the tested exit objective. Compare the ratio against your own frozen rules and comparable trade groups.
It can support a candidate target after you group comparable trades and study the distribution. Before trusting it, replay the full price paths in order, include costs, and validate on separate data.
Bereit, diszipliniertes Risiko auf Krypto anzuwenden? Entdecken Sie die neuen Krypto-Instrumente von Audacity Capital und bringen Sie Ihre Trading-Strategie mit.
Mehr erfahrenNewsletter
Treten Sie unserem Newsletter bei, um auf dem Laufenden zu bleiben.
Treten Sie unserer sozialen Gemeinschaft bei
Beginnen Sie Ihre Reise heute Mit unserer kostenlosen Testversion
Präsentieren Sie stolz Ihre Fähigkeiten und Leistungen durch Zertifikate und erhalten Sie Anerkennung für Ihre harte Arbeit und Ihr Engagement von potenziellen Investoren und Kollegen.
Kostenlose TestversionVerwandte Artikel
Risk of Ruin in Trading: Formula, Examples and How to Reduce It
Learn what risk of ruin in trading means, how the formula works, what affects it, and how position sizing can reduce the chance of account failure.

Sortino Ratio in Trading: How It Measures Downside Risk
Learn what the Sortino Ratio means, how to calculate it using downside deviation, and how traders use it to compare risk-adjusted performance.
Sharpe Ratio: Formula, Calculation, Uses and Limitations
Learn how the Sharpe ratio works, how to calculate it, what a good score means, and where it can mislead investors, portfolios, and trading strategies.
How to Use Anchored VWAP in Trading
Learn how Anchored VWAP works, choose meaningful anchor points, read price reactions, compare it with VWAP, and avoid common mistakes.