

PDT Rule Explained: Pattern Day Trader Rules & 2026 Changes


The PDT rule once limited frequent day trading in margin accounts through two familiar requirements:
- Four or more day trades within five business days.
- $25,000 in minimum equity.
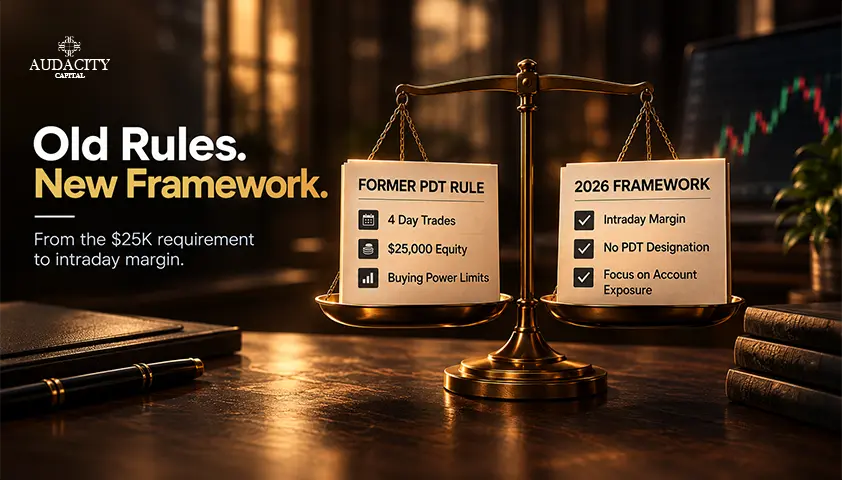
FINRA replaced that framework on June 4, 2026, with new intraday margin requirements based on account exposure instead of a simple trade count. The PDT rule change is significant, but the transition is not identical at every brokerage. Firms can continue moving to the new framework through October 20, 2027.
What Is the PDT Rule?
The PDT rule was a FINRA margin requirement that applied to customers who frequently opened and closed positions within the same trading day. Under the former framework, a trader who met the pattern day trader definition had to maintain at least $25,000 in account equity and was subject to specific limits on day-trading buying power.
What is the PDT rule in simple terms?
Under the former rules, the framework operated by connecting frequent intraday trading with additional margin requirements. A customer who executed four or more day trades within five business days could be classified as a pattern day trader when those trades represented more than 6% of total trades during that period.
The rule also required qualifying accounts to maintain $25,000 in equity. Day-trading buying power was calculated using the account's previous-day equity and maintenance margin excess, subject to the FINRA formula.
Why did the PDT rule exist?
FINRA introduced the special requirements to address the risks associated with leveraged intraday trading. A trader using margin could build a large position relative to available capital, so the framework required additional equity and restricted buying power when certain trading patterns appeared.
What changed in 2026?
FINRA's new framework removed the former PDT provisions and replaced them with intraday margin requirements. Instead of relying on a four-trade threshold, firms now assess whether an account has enough equity to support its intraday positions.
That distinction matters because a guide explaining only the old $25,000 rule can give a trader the wrong picture of the rules applying today.
What Is a Pattern Day Trader?
Under the former FINRA framework, a pattern day trader was a customer who executed four or more day trades within five business days, provided that day trades represented more than 6% of the customer's total trades in the same five-business-day period. The rule applied to margin accounts and came with additional equity and buying-power requirements.
How was a trader classified as a pattern day trader?
The former test had two parts:
- The customer had to execute at least four day trades within five business days.
- Those day trades had to account for more than 6% of the account's total trades during that period.
FINRA also allowed a firm to designate an account when it had a reasonable basis to believe the customer would engage in pattern day trading.
That meant the four-trade threshold was not the only route to designation. A broker could apply the classification based on what it reasonably expected from the customer's trading activity.
Is "pattern day trader" still a designation in 2026?
Not under FINRA's new framework. The June 4, 2026 rule change removed the former PDT provisions and replaced them with intraday margin requirements that focus on the equity available to support positions during the trading day.
However, the transition is important. FINRA permits firms to move to the new framework through October 20, 2027. A brokerage may therefore still be operating under the former requirements until it completes its transition. FINRA advises customers to check directly with their firm to understand which framework applies to their account.
For that reason, some guides still accurately describe the historical PDT rule. But traders should not assume the current four-trade threshold and $25,000 minimum as though they automatically govern every margin account today.
Who Does the PDT Rule Apply To?
The former PDT rule applied to customers who traded securities in a margin account and met the regulatory definition of a pattern day trader. It was not a general rule requiring every active trader to maintain $25,000.
Margin accounts
Under the former FINRA framework, the PDT provisions applied to qualifying day-trading activity in margin accounts. A margin account allows a trader to borrow from the brokerage firm, which creates additional exposure when positions move sharply against the account. The old framework therefore combined trading-frequency requirements with minimum equity and buying-power limits.
What about cash accounts?
The former PDT designation did not apply to cash accounts. That did not make cash trading unrestricted, however. Traders still had to follow cash-account rules, including requirements concerning when purchased securities could be paid for and sold. With most U.S. securities now settling on T+1, understanding available and settled cash remains important.
Stocks, options and other securities
The former FINRA day-trading margin framework covered day trading in securities such as stocks and options. It should not be treated as a universal rule for every market or trading product. Different markets can operate under different regulatory frameworks.
The key point is simple: The PDT rule was not a rule saying that anyone who trades frequently needs $25,000. It was a former margin-account requirement tied to a specific regulatory definition of day trading.
What Counts as a Day Trade?
Under the former FINRA framework, a day trade occurred when a trader bought and sold, or sold and bought, the same security within the same trading day in a margin account. The definition applied to both long and short transactions.
Buying and selling the same security on the same day
Suppose a trader buys 200 shares of a stock in the morning and sells those shares later that same day. Under the former rules, that round trip counted as one day trade.
The same principle applied when a trader sold short and later bought the shares back on the same day.
Short selling and buying back
A short sale followed by a purchase to cover the position on the same day was also treated as a day trade under the former framework. The direction of the trade did not change the basic calculation.
What did not count as an intraday round trip?
A position opened on one trading day and closed on another was not an intraday round trip. For example, buying shares on Monday and selling them on Tuesday would not constitute a day trade under the former definition.
There were also specific circumstances involving existing positions and multiple transactions that could affect how a broker counted trades. That is why traders should rely on their firm's trade records instead of assuming that every order produces one day-trade count.
Does buying and selling the same stock on the same day count as a day trade? Yes, under the former FINRA margin-account definition.
The distinction remains useful today because the transaction itself can still be an intraday trade, even though the 2026 framework no longer uses the old trade count to create a PDT designation.
The Four-Day-Trades-in-Five-Business-Days Rule
The four-day-trades-in-five-business-days test was the part of the former PDT rule that traders knew best. It did not simply mean that making a fourth day trade automatically created a PDT violation. The old framework also included a 6% test.
How does the five-business-day window work?
The former rule looked at a rolling five-business-day period. If a customer executed four or more day trades during that period, the account could meet the first part of the pattern day trader definition. The broker then considered those day trades against the customer's total trading activity during the same period.
The 6% condition
The second part is often left out of simplified explanations.
Under the former framework, the day trades also had to represent more than 6% of the customer's total trades in the margin account during the relevant five-business-day period. If the day trades represented 6% or less of total trades, the customer did not meet the former PDT definition on that basis.
A simple four-trade example
Imagine a trader made one qualifying day trade on Monday, Tuesday, Wednesday, and Thursday. By Thursday, the account had reached four day trades within the five-business-day window.
If those trades also represented more than 6% of the account's total trades during the period, the account met the former PDT definition.
Why the old trade counter matters less in 2026?
This calculation is now mainly relevant for understanding the former system. FINRA's new intraday margin framework removed the PDT designation and no longer uses a four-day-trade threshold to determine whether a trader falls under the old PDT restrictions. Firms have a transition period through October 20, 2027, however, so traders should check which framework their brokerage has implemented.
The $25,000 Minimum Equity Requirement
The former $25,000 threshold was one of the defining features of the PDT rule, but it is often described too simply.
It was a minimum equity requirement for an account classified as a pattern day trader. Equity could include cash and eligible securities, so the rule did not require traders to keep $25,000 in unused cash. FINRA's rules required the minimum equity to be in the account before pattern day trading could continue.
The consequence of falling below the threshold was straightforward. The account could not continue making day trades under the former PDT framework until the minimum was restored. Separate buying-power deficiencies could also create a special maintenance margin call, with specific consequences if the trader failed to meet it within the required period.
The old system also limited how much a qualifying trader could deploy intraday. For equity securities, FINRA generally defined day-trading buying power as four times the previous day's maintenance margin excess.
Does the $25,000 requirement still apply?
No. The $25,000 PDT minimum was removed when FINRA replaced the former day-trading margin provisions with its intraday margin framework. The new system focuses on whether the account has enough equity to support its positions during the trading day.
Traders should still check their broker's requirements. FINRA's current guidance states that $2,000 is the minimum equity required to use margin, but firms may require more and can apply their own house requirements.
PDT Rule Example
A simple example shows why the old PDT rule and the 2026 framework should not be treated as the same system.
Suppose a trader had $20,000 in margin-account equity before the 2026 change. The trader then completed four qualifying day trades within five business days. Under the former rules, that activity could trigger PDT classification, assuming the applicable trade-count conditions were met. Because the account had less than $25,000 in equity, the trader could not continue pattern day trading until the minimum was restored.
The same four trades do not produce the same result under the new framework.
After a broker transitions to the new system, FINRA no longer uses the four-trade count to create a PDT designation. Instead, the firm monitors intraday margin and the equity supporting the trader's positions.
What Changed to the PDT Rule in 2026?
The PDT rule change fundamentally altered how FINRA approaches frequent intraday trading in margin accounts.
FINRA's amended Rule 4210 became effective on June 4, 2026, following SEC approval of the rule change on April 14. The amendment replaced the former day-trading margin provisions with an intraday margin framework.
- The first major change was the removal of the pattern day trader designation. A trader is no longer classified as a PDT simply because the account reaches the former four-day-trades-in-five-business-days threshold.
- The second was the removal of the $25,000 PDT equity requirement. The new framework does not impose that former threshold on day traders. Margin trading still requires sufficient equity, however, and brokers may establish higher house requirements.
- The third change was the move away from a trade counter as the primary regulatory control. Firms now monitor whether account equity remains adequate relative to intraday positions. When an account develops an intraday margin deficit, the firm must address the exposure under its chosen implementation method.
There is one important qualification. FINRA allowed firms an 18-month transition period ending October 20, 2027. A brokerage can therefore remain on the former day-trading framework while it completes its transition.
For that reason, the PDT rule change date should not be interpreted as the date when every broker necessarily changed its customer-facing rules.
What Replaced the PDT Rule?
The former PDT rule was built around a trading-frequency test. The 2026 framework takes a different approach by focusing on intraday margin exposure.
From trade counting to intraday margin
Under the new system, completing a certain number of day trades does not by itself create a regulatory PDT designation. Instead, the broker must ensure that the account maintains adequate equity relative to its positions during the trading day.
What is intraday margin?
Intraday margin refers to margin requirements applied to positions during the trading session. The purpose is straightforward - the amount of risk in an active margin account can change rapidly as positions and market prices change. The new framework allows firms to monitor that exposure using intraday information.
What happens when an account has an intraday margin deficit?
If an account does not have enough equity to support its intraday positions, it can develop an intraday margin deficit. FINRA's framework requires the deficit to be addressed promptly, with firms given flexibility in how they monitor and manage these situations.
Why broker implementation matters?
This is where traders need to look beyond the headline PDT rule change.
FINRA allows firms to use different methods for monitoring intraday margin. A broker may use real-time controls, an end-of-day calculation based on intraday exposure, or a combination of approaches. Firms can also impose stricter house requirements.
So the new framework removes the old PDT threshold, but it does not remove margin controls.
What Happens If You Violate the PDT Rule?
The consequences depend on which framework governed the account. Under the former PDT rule, a trader who triggered a day-trading margin call had five business days to meet the call. If the requirement was not satisfied, the broker could impose restrictions on the account, including the former 90-day restriction on day trading. FINRA's historical investor guidance explains these requirements in detail.
The 2026 framework works differently. Once a broker transitions to the new intraday margin requirements, the key issue is no longer the number of day trades but whether the account has enough equity to support its intraday positions. If an account develops an intraday margin deficit, the trader is expected to satisfy the deficit promptly, either by providing additional funds or reducing the relevant exposure. Repeated failures to address deficits can result in account restrictions of up to 90 days.
That distinction matters. A violation under the old system was primarily linked to the PDT trade-counting and equity requirements, whereas the new framework focuses on the account's actual intraday margin exposure.
How to Avoid PDT Violations?
The best answer to how to avoid PDT rule restrictions depends on whether your broker has completed its transition to FINRA's new intraday margin framework. During the permitted transition period, some firms may continue operating under the former requirements, while others may already use the new system. FINRA specifically advises traders to check with their brokerage firm to understand which framework applies to their account.
If your broker still operates under the former framework, monitor your day-trading activity, understand the five-business-day counting period, and maintain the required equity. The old rules made trade frequency particularly important for accounts below the $25,000 threshold.
If your broker has moved to the new framework, the focus changes. Monitor your available buying power and intraday margin requirements, understand how your broker calculates exposure, and avoid entering positions that could create an intraday margin deficit. Your broker may also impose requirements that are stricter than the regulatory baseline.
In other words, how to avoid PDT rule problems in 2026 is no longer simply a matter of counting trades. The safer approach is to know which framework your broker uses and understand the margin requirements attached to your account.
Does the PDT Rule Apply to Cash Accounts?
No. The former PDT rule was a margin-account framework. FINRA's historical definition described a day trade as buying and selling, or selling and buying, the same security on the same day in a margin account.
Cash-Account Restrictions Are Different
A cash account does not provide the same borrowing facility as a margin account, so the regulatory issue is different. Securities purchases generally must be paid for in full, and traders must account for the applicable settlement requirements and restrictions on using unsettled proceeds.
For U.S. securities covered by the standard settlement cycle, transactions settle on T+1, meaning settlement generally occurs one business day after the trade date. FINRA explains the practical implications of the T+1 cycle for investors.
Why the "$25,000 to Day Trade" Statement Can Mislead?
The familiar statement that a trader needs $25,000 to day trade came from the former margin-account PDT framework. It should not be presented as a universal rule for every type of trading account.
The 2026 FINRA change removed the former $25,000 PDT minimum from the new intraday margin framework. However, cash accounts remain subject to their own settlement requirements, while brokers can impose account-specific conditions.
PDT Rule vs Margin Account
The distinction becomes clearer when the account types are compared directly:
Account feature | Cash account | Former margin framework | 2026 margin framework |
Broker credit | No | Yes | Yes |
Former PDT designation | No | Yes | Removed under the new FINRA framework |
Former $25,000 PDT requirement | No | Yes | Removed |
Intraday margin requirements | Not the same margin framework | Former day-trading margin rules | Applies once the broker transitions |
Settlement requirements | Yes | Yes | Yes |
Broker house requirements | May apply | May apply | May apply |
The important point is that the PDT rule was never simply a rule about being an active trader but a part of the margin framework governing certain frequent intraday activity. FINRA's 2026 amendment removed the former pattern day trader definition and $25,000 requirement, replacing those provisions with intraday margin requirements that assess account equity against intraday positions.
The regulatory change therefore affects margin-based day trading, not every account or every type of active trading.
Can You Day Trade Without Triggering the PDT Rule?
Yes, but the answer depends on whether your broker has transitioned to FINRA's new framework.
Under the Former Framework
Before the 2026 change, traders could avoid the former PDT designation by staying below the applicable day-trade threshold, using a cash account subject to its own settlement rules, or maintaining the required $25,000 equity in a qualifying margin account. The former framework counted day trades over a five-business-day period and applied additional buying-power requirements to designated accounts.
Under the New Framework
The PDT rule change removes the former trade-counting trigger. Once a brokerage adopts the new intraday margin requirements, executing several intraday trades does not by itself create a pattern day trader designation. Instead, the broker assesses whether the account has sufficient equity relative to its intraday positions.
What You Still Cannot Ignore
Removing the former PDT designation does not remove margin risk. Traders still need to understand:
- Intraday margin requirements, which relate account equity to the positions held during the trading day.
- Buying power and exposure, because the amount a broker allows you to trade depends on its risk controls.
- House requirements, since a brokerage can impose requirements above the regulatory baseline.
- Transition status, because firms have until October 20, 2027, under the permitted transition period to implement the new requirements.
So, while the old trade counter is being phased out, the need to understand your broker's margin rules remains.
Conclusion
The former PDT rule tied frequent intraday trading to a $25,000 equity requirement and a trade-counting framework. That model changed on June 4, 2026, when FINRA introduced its new intraday margin requirements. Yet the transition is not identical across every brokerage, so traders should confirm which framework their firm currently uses and understand the margin requirements that apply to their account.
For traders who want to understand how regulation works in practice, Audacity Capital provides trading programmes and resources to explore further.
FAQs
The PDT rule is a former FINRA margin framework that classified certain frequent day traders and required designated accounts to maintain at least $25,000 in equity.
The former PDT framework is being replaced by FINRA's intraday margin requirements, effective June 4, 2026, with a permitted transition period through October 20, 2027.
The PDT rule change date is June 4, 2026, when FINRA's new intraday margin requirements became effective.
No. The new FINRA framework removes the former $25,000 minimum equity requirement for day trading, although brokers may impose their own requirements.
FINRA replaced the former day-trading provisions with an intraday margin framework that evaluates account equity against intraday positions rather than relying on the old PDT trade counter.
Yes, under the new framework, the former $25,000 PDT minimum no longer applies. Your broker's margin requirements and implementation status still determine what trading activity it permits.
Under the new framework, trade counting no longer creates the former PDT designation once your broker transitions. Traders should instead understand their intraday margin requirements and avoid unresolved margin deficits.
¿Listo para aplicar un riesgo disciplinado a las criptomonedas? Explore los nuevos instrumentos de cripto de Audacity Capital y traiga su estrategia de trading.
Aprender másBoletín
Únase a nuestro boletín para mantenerse al día.
Únete a Nuestra Comunidad Social
Comienza Tu Viaje Hoy Con Nuestra Prueba Gratuita
Muestra con orgullo tus habilidades y logros a través de certificados y obtén reconocimiento por tu arduo trabajo y dedicación de posibles inversores y compañeros.
Prueba GratuitaArtículos Relacionados
Day Trading Tips: The Rules That Actually Decide Whether You Survive
Practical day trading tips ordered by what actually matters. Risk rules, discipline, execution, and the 2026 pattern day trader change explained honestly.

Day Trading Crypto vs Stocks: Which Is Better?
Compare crypto and stock day trading by hours, volatility, fees, liquidity, rules and risk to find which market fits your trading style.
How to Create a Day Trading Risk Management Plan?
Build day trading risk management strategies with daily loss limits, position sizing rules, drawdown controls, and a practical trading checklist.
Best Moving Average for Day Trading in 2026
Compare the 9, 20, 50 and 200 moving averages for day trading, when each works best, and how to avoid lag, noise and false signals.