

ICT Silver Bullet Strategy: Windows, Setup and Execution Rules


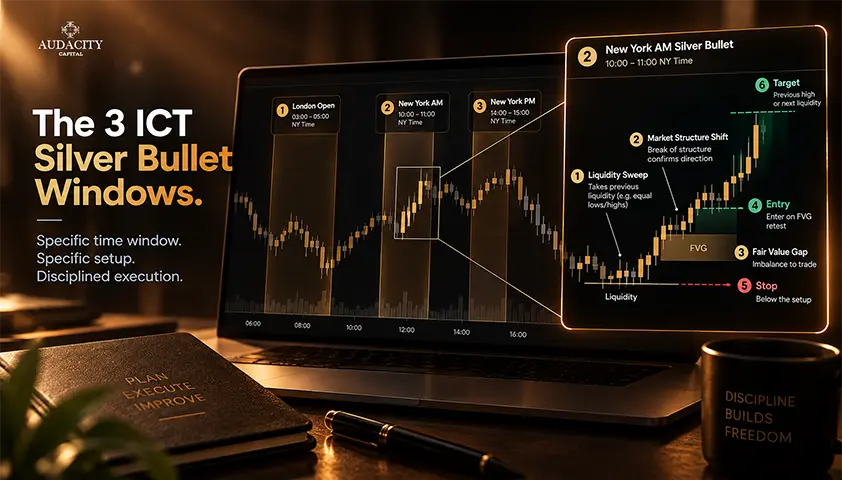
If you have read three guides on this strategy, then you must have read three different versions of it. One instructs you to enter on the fair value gap right after the liquidity sweep. The other will tell you to see a market structure change first.
The timing of the London window varies by an hour depending on which site you came across. This can really become a very frustrating experience for you when you try to execute the rule on a one-minute chart.
In this article, you will be able to find all the trading windows, along with the complete execution process including those that are often overlooked by many of the guides. Also, you will learn the entry and stop rules that are used by the practitioners.
This is educational material, not a piece of investment advice. There is significant risk of loss associated with trading and most retail traders lose money.
What Is the ICT Silver Bullet Strategy?
The ICT Silver Bullet strategy is a time-based intraday model based on the Inner Circle Trader system of Michael J. Huddleston. The strategy limits trading to three one-hour windows throughout the day.
Within those windows, it searches for price to find liquidity and move in the opposite direction of the pool. The move should leave behind a fair value gap which the trader then enters on the retracement.
There are two concepts that define the entire model.
A fair value gap is an area of price that moves through so fast that it is left unbalanced. Practitioners believe that price will return to it to close that gap later.
Buy-side and sell-side liquidity is the level where stop orders are expected to settle. Buy-side liquidity is above old highs and sell-side liquidity is below old lows. Price is assumed to be drawn toward these pools.
The idea behind it, that price chases liquidity during certain hours of the day, is a practitioner theory. This is not something that has been proved to be a characteristic of the market, and nothing here in this article is meant to prove that claim.
The Three Silver Bullet Windows
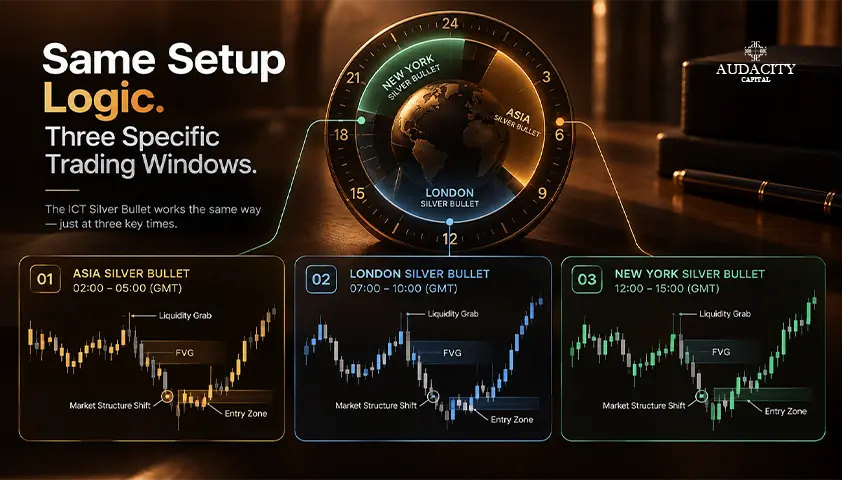
The ICT Silver Bullet times are defined in New York local time and consist of three one-hour intervals. All three are listed below with a GMT reference.
Daylight saving time is the point at which the two guides differ greatly from each other. This is important since making a mistake will place you an hour away from the chart.
One of the well-known guides sets the London window as 3 to 4 AM EST in winter and 2 to 3 AM in summer. Another states that the windows never change their positions in New York Local Time; only the name changes from EST to EDT twice a year.
Instead of choosing sides, here's the solution. The windows are based on New York local time. If the chart works in New York local time, no adjustments are needed.
Traders from a country that does not observe US daylight saving time will notice that the equivalent local time is moved by an hour twice a year. That is where the apparent contradiction comes from.
Practical recommendation: Set your chart timezone to New York and leave it. This takes away the problem altogether. It's also one of the most frequent questions within the guide's comment thread.
Window | New York local time | GMT (verify before publishing) | Notes |
London open | 03:00 to 04:00 | 08:00 to 09:00 (winter) | Suits forex majors |
New York AM | 10:00 to 11:00 | 15:00 to 16:00 (winter) | Cited as the most active of the three |
New York PM | 14:00 to 15:00 | 19:00 to 20:00 (winter) | Lower participation than the AM window |
The Setup, Step by Step
This is the heart of the Silver Bullet trading strategy, and here the guides go their separate ways. The entire sequence is below with the divergence marked where it happens.
Before the window. On the 15-minute chart, mark the closest liquidity in the buy and sell zone.
Practitioners focus on the previous day's high and low, the previous session's high and low, and established 15-minute swing points. The relative equal highs and lows are a secondary reference.
The order of the sequence inside the window:
- Wait for the window to open. Do not pre-position.
- Watch the price action sweeping one side of the marked liquidity.
- Drop to a one, three or five minute chart.
- Wait for the market to change towards the other liquidity pool. Search for a decisive candle with a fair value gap to follow.
A market structure shift is a recent swing point break that indicates a change in the short-term trend in price.
- Mark that gap.
- Wait for the price action to retrace into this gap.
- Enter there.
The difference, in a nutshell. Two out of three ranking pages referenced in this article do not mention the market structure shift. They advise the reader to enter the fair value gap right after the sweep.
The reference page requires the structure shift and lists entering without it as the second most prevalent cause of a failed entry.
Both approaches are possible, so let us find out what role the step plays. Without a structure shift, a sweep and continuation look the same as a sweep and reversal.
The structure shift is what helps differentiate between the two. If the step is skipped, then you won't know if price is turning or continuing to trend further in the direction it swept.
Optional filter employed by certain practitioners: verify the fair value gap against the premium or discount compared to the recent swing. This is an addition to the procedure, not a mandatory step.
Entry, Stop and Target
There are three execution decisions at the end of the ICT Silver Bullet setup and the sources differ on each of these. Instead of averaging them, here is each decision with its variants and the trade-off.
Entry
The typical strategy uses a limit order placed just outside the fair value gap in the direction you are planning on trading. The order gets executed as price reverts back into the gap.
Alternatively, some practitioners prefer to wait for the reaction inside the gap rather than placing an order. It provides you with confirmation, but a poorer fill, as the price can turn without ever reaching your entry.
Stop
Two methods come into play here. In one, the stop goes slightly past the candle that was responsible for creating the gap. That's short, and according to one expert, is always marked when used without any buffer zone.
The other method places it slightly past the swing point generated from the sweep. It is wider, can survive more noise, and increases your risk-to-reward on every trade.
Both are equally real, and the choice is yours.
Target
The objective mentioned above is precisely the reverse liquidity pool you identified prior to the window. Some sources, however, opt for a fixed risk-to-reward ratio.
They are two different approaches for generating two different targets.
The pool-based target is the one that adheres to the model's own logic, since the model's whole premise is that price is drawn to liquidity.
Timing is one element to keep in mind: while the pattern emerges within an hour-window, the trade itself may take more time to hit its target. This is a common misconception addressed specifically in the guide.
It should be noted that there is no required risk-to-reward ratio, pip expectancy, risk percentage or stop buffer specified as a rule here. If a source suggests any of these figures, they are referenced accordingly.
Decision | Common approach | Alternative and its cost |
Entry | Limit order at the edge of the fair value gap | Wait for a reaction inside the gap, at a worse price |
Stop | Beyond the candle that created the gap | Beyond the sweep swing, wider but less often tagged |
Target | The opposite liquidity pool | A fixed risk-to-reward multiple, which ignores structure |
A Worked Example
This is an example of a New York AM window setup for any instrument based on the entire process above:
The liquidity is marked on the fifteen-minute chart prior to the window. There is a distinct buy-side level above the recent highs and a sell-side liquidity pool below.
The window opens, and the price trades above the identified buy-side level, taking out the stops placed there. On the three-minute chart, the structure becomes bearish with a decisive close, leaving a fair value gap behind.
The price retraces into this gap, an entry is made and the stop is placed beyond the candle that created the gap. The target for the trade is the previously identified sell-side liquidity pool.
This is how the setup works out. The alternate scenario happens almost as frequently: the price retraces to the gap and continues straight through it, which invalidates the setup and takes out the stop.
Every ranking page shows only the clean version. Treat this walkthrough as a diagram of the steps, not evidence that the steps pay.
What the Performance Claims Actually Rest On
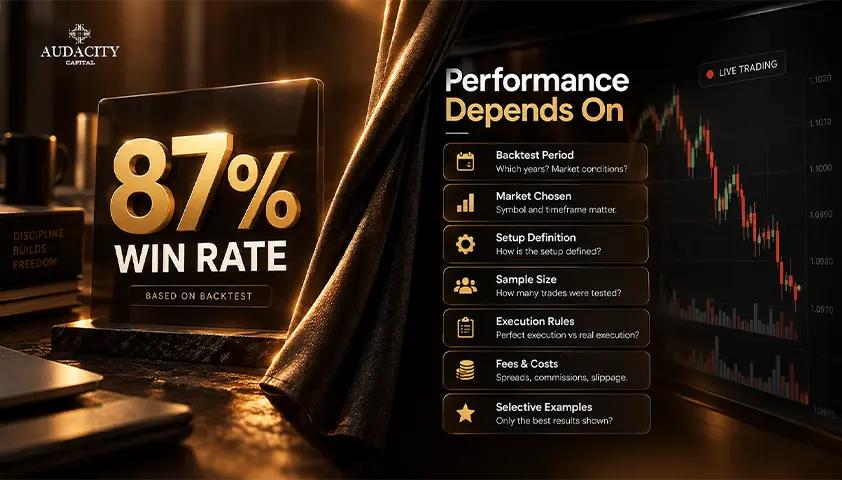
This is the most often overlooked section, which deserves to be considered with care.
The most detailed guide in the area gives an account of a 55% to 65 % win rate at the set risk-to-reward ratio, together with a 20 to 30 pip expectation from each good trade.
These numbers come from the author's observation from discretionary trading. They do not represent any study result. No sample size, instrument, period or rule definition is attached to them.
There is one important detail from the page's own comment thread worth mentioning.
A reader who did forward testing of the strategy for four months requested information about the lowest monthly win rate and the existence of a whole year's performance data. This query was asked three times over several months.
The answer was always that the backtesting for one year would be shared soon. It hasn’t appeared yet. This pattern is the issue, not the individuals involved, and so no website or commentator is cited.
This shows the basis of the numbers reported: an arbitrary number that has not yet been verified through a known sample size.
You can use this strategy exactly as described. You cannot use someone else’s winning percentage as your own. The only relevant numbers that apply to you are the ones from your own logged results.
Where Traders Get It Wrong
This is the set of mistakes commonly mentioned by traders themselves.
- Trading outside the window. The chart pattern can look identical at any hour, but the model is defined by the window. Outside it, the setup does not apply.
- Entering after the sweep without the structure shift. This is the divergence covered earlier. Skip the shift, and you cannot tell a reversal from a continuation.
- Placing the stop flush against the gap candle with no buffer. By one source's own account, a stop placed this tight is routinely tagged before the move develops.
- Choosing the wrong window for the instrument. Forex majors and US index futures behave differently across the three windows. A window that suits one does not automatically suit the other.
- Closing the trade early because the clock has passed the end of the window. The setup must form inside the window. The move it triggers does not have to complete inside it.
Trading the Silver Bullet Under Prop Firm Rules
If you are running this model inside a funded evaluation, the rule set can conflict with the model in ways that catch traders out. None of these are unique to any one firm, so treat them generically.
1. Minimum hold times
Many programmes treat positions held for a very short period as prohibited scalping. The Silver Bullet executes on one to three minute charts, so a fast winner can breach a rule the trader never considered.
2. News restrictions
The New York AM window sits close to scheduled US data releases, and many programmes restrict trading around them. A setup that forms right into a release can be off-limits.
3. Trade frequency and minimum trading days
A model that produces at most a few setups a day interacts awkwardly with rules on maximum frequency or minimum active days.
Before running this model on a funded account, check your programme's current terms. Pay particular attention to minimum hold times, news trading restrictions, and whether your intended instrument and session are permitted.
Verify these against your current agreement rather than assuming.
Conclusion
The ICT Silver Bullet strategy is a fully specified set of rules, which is rare and is most of its appeal. You can pick up the windows, the sequence and the execution decisions and act on them without guessing.
What the model does not come with is evidence. The figures attached to it circulate as estimates repeated between sites, not as tested results.
So build your own number. Pick one window and one instrument. Set the chart to New York local time and log fifty setups.
Record the full sequence, including sessions where no valid setup was formed. That log is the only performance figure that applies to you.
Audacity Capital offers simulated evaluation accounts on MT5 and DXTrade. If you use a funded-account program for testing (prop firm free trial program), verify its current platform availability and account rules before trading.
Related Articles
Frequently Asked Questions
This is the most repeated question in the benchmark guide's comment thread. Practitioners resolve it with premium and discount.
For a short, take the gap sitting in the premium half of the recent swing. For a long, take the gap in the discount half. Some layer entries across both rather than choosing one.
Some practitioners substitute another price delivery array, such as an order block or a breaker. The benchmark guide is explicit that this model is built on the fair value gap specifically.
So the accurate answer is that the setup is simply absent, not that a substitute is equivalent. No gap means no trade.
The benchmark guide's author answers this directly in the thread. Mark the high and low made between the Asian session open and the start of the London window.
That range is complete by the time the 3 AM window opens, so it gives you the liquidity levels to watch as the window begins.
No, and this is a documented source of confusion. The setup must form inside the one-hour window. The move it triggers does not have to be completed inside it.
A trade can be opened during the window and take considerably longer to reach the opposite liquidity pool.
Practitioners are genuinely split. In the benchmark guide's thread, the same author answers "not necessary" in one comment and says a daily bias "will boost results" in another.
Some traders find a higher timeframe filter useful, others find it adds hesitation. There is no settled answer, so test both against your own log.
暗号資産に規律あるリスクを適用する準備はできていますか?Audacity Capitalの新しい暗号資産商品を探索し、あなたの取引戦略を持ち込んでください。
詳細を見るニュースレター
ニュースレターに登録して最新情報を入手。
ソーシャルコミュニティに参加
関連記事

Martingale Strategy in Trading
How the martingale trading strategy works, what the doubling arithmetic actually costs, why position sizing cannot create an edge, and where it is banned.

Momentum Trading Strategy: A Comprehensive Guide
Master the core principles of a momentum trading strategy. Learn how to use key indicators, manage sharp-reversal risks, and master exit timing.
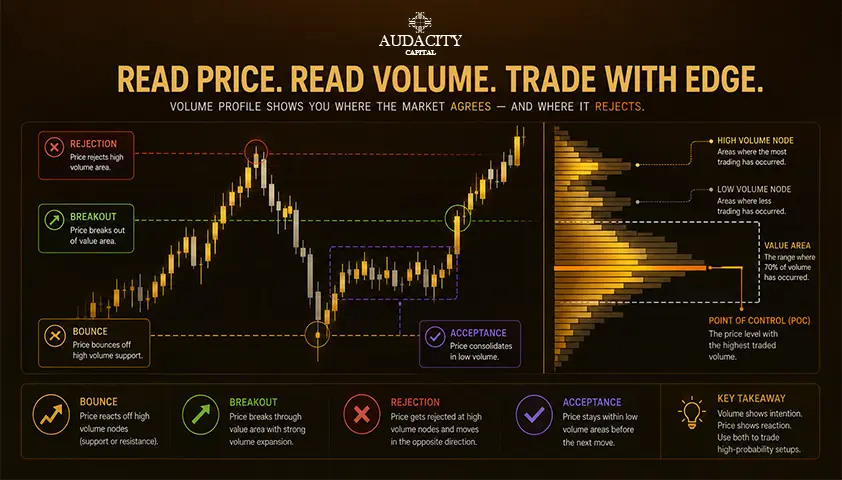
Volume Profile Trading Strategy Guide: Setups & Nodes
A Volume Profile trading strategy shows where the market spent the most volume. Learn POC, value areas, volume nodes, and 4 setups for ES, NQ, and forex.
Mean Reversion Trading Strategy Explained (2026)
Prices that stretch too far tend to snap back to an average, but only in the right market. Learn the tools, the setup, and the trend risk.